

The short answer: a 529 plan is a tax-advantaged education savings account. The money grows without federal tax, and withdrawals are federal tax-free for qualified education costs.
- College: tuition, books, and room and board at qualified schools
- K-12: up to $20,000 a year per beneficiary, starting in 2026
- Other uses: apprenticeships and up to $10,000 of student loans
- Roth rollover: up to $35,000 into a Roth IRA if the account has been open at least 15 years and meets the other rules
- Next step: Plan it with the Sinking Funds Tracker ($4.99).
A 529 plan is a tax-advantaged savings account for education. You put money in for a child (or yourself), it's invested and grows without federal tax, and withdrawals are federal tax-free when they pay for qualified education costs like college tuition, books, and room and board. In 2026, a 529 can also cover up to $20,000 a year of K-12 costs, apprenticeships, up to $10,000 of student loans and, if the account qualifies, a rollover of up to $35,000 into a Roth IRA. Below is how it works in plain English, what it covers, how it compares to other accounts and how to fit it into a family budget.
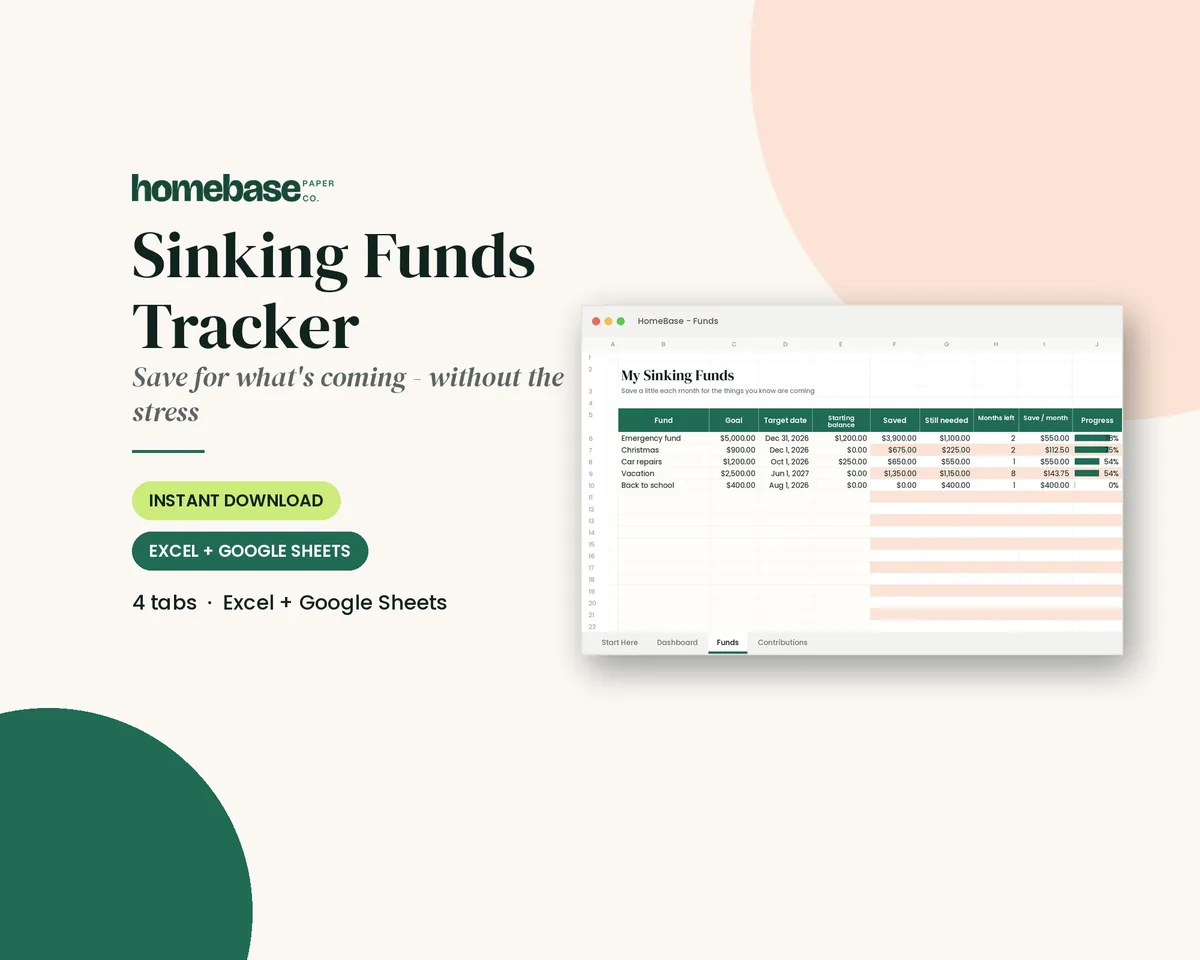
Our Sinking Funds Tracker spreadsheet ($4.99) does the math on how much to set aside each month for every goal, so college savings has a line of its own next to the holidays, the car and everything else.
I worked to put myself through Oakland University, and it took much longer than the usual four years. That taught me slow progress is still progress, and it's why I like plans you can start small and keep going with. A 529 is one of those plans.
What is a 529 plan?
529 plans are legally called "qualified tuition programs." They're named after Section 529 of the Internal Revenue Code and are sponsored by states, state agencies or educational institutions. The SEC's introduction to 529 plans describes two types:
| Type | How it works | Good to know |
|---|---|---|
| Education savings plan | You invest contributions in portfolios the plan offers; the balance rises or falls with the market | The most common type; most are open to residents of any state |
| Prepaid tuition plan | You prepay future tuition at participating colleges, usually in-state public schools, at today's prices | Often has residency rules and covers tuition and fees, not room and board |
Most people searching "529 savings plan" (or "529b savings plan") mean the first type. When this guide says 529 plan, that's the one it means.
How a 529 plan works, step by step
- You open an account. Usually online, directly with a state's plan. You're the account owner.
- You name a beneficiary. That's the future student: a child, grandchild, niece, nephew or even yourself.
- You contribute. One-time deposits, automatic monthly transfers or gifts from family.
- You choose investments. Many families pick an age-based (or "target enrollment") portfolio that gets more conservative as the student nears college.
- The money grows. Earnings aren't taxed federally while they stay in the account.
- You withdraw for qualified costs. Withdrawals for qualified expenses are federal tax-free, and you'll get a Form 1099-Q for the year.
The account owner stays in control of the money, not the child. You decide when to withdraw and can change the beneficiary to another family member.
The tax benefits (and the one limit people miss)
According to IRS Topic No. 313, earnings in a 529 grow tax-free, and distributions aren't taxable when they pay for qualified expenses. One thing that surprises people: contributions aren't deductible on your federal return. The benefit is the tax-free growth and withdrawals.
Many states do offer a state income tax deduction or credit when you contribute to your own state's plan. The rules and amounts vary a lot, so check your state's plan page before you choose.
What a 529 plan can pay for in 2026
Here's the big grouped list. Qualified expenses must be for the account's beneficiary (student loans can also cover a sibling).
College, university and vocational school
- Tuition and required fees
- Books, supplies and required equipment
- Computers, software and internet access used for school
- Room and board, if the student is enrolled at least half-time
- Special-needs services required for enrollment
K-12 school (up to $20,000 per year, per beneficiary, starting in 2026)
- Tuition at public, private or religious schools
- Curriculum, books and instructional materials
- Tutoring or classes outside the home
- Fees for standardized tests, AP exams and college admissions tests
- Dual-enrollment fees
- Educational therapies for students with disabilities from a licensed provider
The K-12 limit was $10,000 a year through 2025. Not every state follows the federal K-12 rules for state taxes, so check before using a 529 for K-12.
Other qualified uses
- Fees, books, supplies and equipment for a registered apprenticeship program
- Certain recognized postsecondary credential programs
- Student loan principal or interest, up to $10,000 per person over a lifetime
- A rollover to the beneficiary's Roth IRA (rules below)
Usually not qualified
- Transportation and travel to campus
- Health insurance or student health fees charged separately
- Application fees for college
- Sports, clubs and other extracurricular costs
- Repaying a student loan beyond the $10,000 lifetime cap
What happens if you use the money for something else
A withdrawal that isn't for qualified expenses splits into two parts. Your original contributions come back without tax. The earnings part is taxed as ordinary income and usually gets a 10% additional federal tax, per the SEC bulletin. There are exceptions to the 10% part, such as when the student gets a tax-free scholarship, but the earnings are still taxed.
If plans change, you have better options than cashing out:
- Change the beneficiary to another family member, like a younger sibling, a cousin or yourself.
- Wait. There's no deadline to use the money, and grad school counts.
- Use it for trade school or an apprenticeship.
- Roll it into a Roth IRA for the beneficiary, if the account qualifies.
The 529-to-Roth IRA rollover rules
Since 2024, leftover 529 money can move into the beneficiary's Roth IRA without tax, if every rule is met:
| Rule | Requirement |
|---|---|
| Account age | The 529 has been open for the beneficiary at least 15 years |
| Five-year rule | Only money contributed (plus its earnings) more than five years earlier can move |
| Transfer | Direct trustee-to-trustee transfer, into the beneficiary's own Roth IRA |
| Yearly cap | The Roth IRA contribution limit for the year ($7,500 in 2026), less any other IRA contributions |
| Lifetime cap | $35,000 per beneficiary |
The 15-year clock is one more reason to open an account early, even with a small first deposit.
How much can you put in a 529 plan?
There's no federal annual contribution limit. Each state plan sets a lifetime maximum per beneficiary, and the IRS says contributions can't be more than what's needed for the beneficiary's qualified education expenses.
Gift tax rules still apply. According to the IRS gift tax FAQ, the annual exclusion is $19,000 per person in 2026. A married couple who split gifts can give $38,000 per child. 529 plans also allow a special election to treat one large gift as if it were spread over five years, up to $95,000 per person, which grandparents sometimes use.
529 plan vs. other ways to save for school
| Account | Tax break | Limits | Best for |
|---|---|---|---|
| 529 plan | Tax-free growth and qualified withdrawals; many states add a deduction | No federal annual limit; state lifetime caps | Most families saving for college or K-12 |
| Coverdell ESA | Tax-free growth and qualified withdrawals | $2,000 per beneficiary per year; income limits apply | Small balances with more investment choice |
| Roth IRA | Contributions can come out anytime; earnings rules apply | $7,500 in 2026, with income limits | Parents who want retirement first, college second |
| Custodial account (UTMA/UGMA) | Limited | None, but it becomes the child's money at adulthood | Savings that might not go to school |
| High-yield savings account | None on interest | None | Money needed within a few years |
For most families, the 529 offers the biggest tax break for education with the most flexibility. A high-yield savings account still makes sense for short-term costs like a laptop or move-in day.
How a 529 affects financial aid
A parent-owned 529 is reported on the FAFSA as a parent asset, which generally counts against aid much less than money in the student's name. Since the simplified FAFSA began with the 2024-25 school year, 529s owned by grandparents or other relatives aren't reported on the FAFSA at all. Some private colleges use the CSS Profile, which can still ask about them.
How to choose a 529 plan in 5 steps
- Check your state's plan first. If your state gives a tax deduction or credit only for its own plan, that's a real head start.
- Compare fees. Look at the total annual cost of each portfolio. Direct-sold plans are usually cheaper than plans sold through an advisor.
- Look at the investment choices. Age-based portfolios are the simplest; static portfolios let you choose your own mix.
- Read the plan's offering document. It lists fees, investment options and the state's rules.
- Set up automatic contributions. Even $25 or $50 a month builds the habit.
How much to save: a starter plan
You don't need to save the whole cost of college. Many families aim for a share and plan to cover the rest with current income, scholarships and aid. Here's what steady monthly deposits add up to before any investment growth:
| Monthly deposit | After 5 years | After 10 years | After 18 years |
|---|---|---|---|
| $25 | $1,500 | $3,000 | $5,400 |
| $50 | $3,000 | $6,000 | $10,800 |
| $100 | $6,000 | $12,000 | $21,600 |
| $250 | $15,000 | $30,000 | $54,000 |
These are contributions only. Investment growth can add a lot over 18 years, but it isn't guaranteed. To see how growth compounds, try our free compound interest calculator or read what compound interest is.
Starter version, if money is tight:
- Build a starter emergency fund first.
- Open the 529 with whatever minimum your plan allows.
- Set a small automatic monthly deposit on payday.
- Ask family to give to the 529 for birthdays and holidays instead of more toys.
- Raise the deposit by $10 or $25 each time you get a raise or pay off a bill.
How to fit a 529 into your family budget
A 529 works best when it's a line in your budget, not leftover money. Put it with your other savings goals, after essentials and your emergency fund. Our guide to the cost of raising a child shows how education fits into the bigger picture.

The Sinking Funds Tracker ($4.99) gives college its own monthly target next to your other goals. The Annual Budget Spreadsheet ($6.99) shows the whole year at once, so you can see what a $50 or $100 monthly deposit means for everything else. If you want both, the Ultimate Budget Bundle has all six spreadsheets plus both printable planners for $19.99 (reg. $46.42 bought separately). Browse them all in our Spreadsheets shop.
This guide is general education, not tax or investment advice. Check your state plan's documents, and talk with a tax professional if your situation is complicated.
Saving for more than school? Our guide to investing for kids compares custodial accounts, Roth IRAs for teens and Trump Accounts.
Make it easier
Tools for this
Spreadsheets
Sinking Funds Tracker
It does the math: how much to set aside each month to hit every goal on time.

Spreadsheets
Annual Budget Spreadsheet
See exactly where your money goes every month - without complicated software.
 Save 57%
Bundles
Ultimate Budget Bundle
All 6 spreadsheets + both printable planners - for less than half the price of buying them separately.
Frequently asked questions
What is a 529 plan? A 529 plan is a tax-advantaged savings plan for education, sponsored by a state, a state agency or an educational institution under Section 529 of the tax code. Money grows without federal tax, and withdrawals are federal tax-free when they pay for qualified education expenses.
How does a 529 plan work? You open an account, name a beneficiary, contribute money and pick investments, usually an age-based portfolio. The earnings grow federal tax-free, and you withdraw money tax-free to pay qualified costs like tuition, fees, books, and room and board for a student enrolled at least half-time.
What is a 529b savings plan? A "529b savings plan" is usually just another way of searching for a 529 education savings plan; the "b" often comes from Section 529(b) of the tax code, which defines what a qualified tuition program is. There's no separate account type called a 529b plan.
What can a 529 plan be used for in 2026? In 2026, a 529 plan can pay for college and vocational school costs, up to $20,000 a year of K-12 tuition and related expenses, registered apprenticeship costs, certain postsecondary credential programs and up to $10,000 of student loan repayments per person over a lifetime.
How much can I contribute to a 529 plan? There's no federal annual contribution limit for a 529 plan, but each state plan sets a lifetime maximum per beneficiary. For gift tax purposes, you can give up to $19,000 per person in 2026 without using any of your lifetime exemption, or elect to spread a gift of up to $95,000 over five years.
Are 529 contributions tax deductible? No, 529 contributions aren't deductible on your federal tax return, according to the IRS. Many states do offer a state income tax deduction or credit for contributing to their own plan, so check your state's rules before you choose a plan.
What happens if my child doesn't go to college? If your child doesn't go to college, you can change the beneficiary to another family member, save the money for later or graduate school, use it for trade school or an apprenticeship, or roll up to $35,000 into the beneficiary's Roth IRA if the account qualifies. Withdrawing it for other uses means income tax plus a 10% additional tax on the earnings.
What is the penalty for using 529 money for non-qualified expenses? The earnings portion of a non-qualified 529 withdrawal is taxed as ordinary income and usually hit with a 10% additional federal tax. Your original contributions come back without tax, and the 10% doesn't apply in certain cases, such as when the student receives a tax-free scholarship.
Can I roll a 529 plan into a Roth IRA? Yes, a 529 can roll into the beneficiary's Roth IRA tax-free, up to $35,000 over a lifetime, if the account has been open at least 15 years, the money moved was contributed more than five years earlier, and it goes by direct trustee-to-trustee transfer. Each year's rollover is capped by the Roth IRA contribution limit, which is $7,500 in 2026.
Do I have to use my own state's 529 plan? No, most 529 education savings plans are open to residents of any state, and the money can be used at eligible schools nationwide. Your own state's plan may still be the better deal if it gives you a state tax deduction or credit.
How does a 529 plan affect financial aid? A parent-owned 529 plan is reported on the FAFSA as a parent asset, which generally counts against aid far less than money held in the student's name. Since the simplified FAFSA started with the 2024-25 school year, 529 plans owned by grandparents or other relatives aren't reported on the FAFSA.
Can grandparents open a 529 plan? Yes, anyone can open a 529 plan for a child, including grandparents, aunts, uncles and family friends, and anyone can usually contribute to an existing account. Grandparent-owned accounts no longer show up on the FAFSA, though some private colleges' CSS Profile still asks about them.
When should I start a 529 plan? The best time to start a 529 plan is as early as you can, because more years of tax-free growth do more of the work. Starting with a small automatic deposit you can keep up is better than waiting for a big lump sum.
How do I budget for 529 contributions? Treat 529 contributions as a monthly bill that gets paid on payday, after essentials and your emergency fund. Our Sinking Funds Tracker spreadsheet ($4.99) does the math on how much to set aside each month for college alongside every other savings goal, so one goal doesn't quietly crowd out the rest.
More from HomeBase
You may also like

Printables
Budget Planner Printable
Twelve undated pages you can print every month: budget, bills, spending, savings and debt.

Spreadsheets
Bill Tracker Spreadsheet
Bills due in 3 days or less light up red, so nothing slips through.

Spreadsheets
Paycheck Budget Spreadsheet
Enter your bills once. The sheet tells you which paycheck pays each one, all year.

Spreadsheets
Zero-Based Budget Spreadsheet
The 'Left to budget' counter turns green when every dollar has a job.
 Club
Monthly club
Money Club
Anyone who wants a clear plan for the month's bills, holiday spending and savings.
Free printable
Give every dollar a job: get the free monthly budget template
A printable zero-based monthly budget: income, bills, everyday spending and savings on one page, with a planned vs. actual column. You'll also get our weekly HomeBase email with simple budgeting and bill-paying tips.
