
 The Holiday Collection

The short answer: buy now, pay later for Christmas can work for one or two planned gifts that already fit your budget, with every payment date on your bill calendar. If a purchase only fits when it's split into four, it doesn't fit yet.
- The risk: stacked plans land in late December and January, right when regular bills arrive
- Federal Reserve data: 26% of BNPL users paid late at least once in the past year, and 17% were charged extra
- Remember: it's still a loan, payments usually come out automatically and each lender only sees its own loans
- Already using it? List every active plan, add up what's owed and compare it with your next paychecks
- Next step: Plan it with the Bill Tracker Spreadsheet ($4.99).
Buy now, pay later for Christmas can work if you use it for one or two planned gifts that already fit your holiday budget, put every payment date on your bill calendar, and keep the money for each payment set aside in checking. It goes wrong when several plans pile up at once, because the payments land in late December and January, right when regular bills and post-holiday bills arrive. If a purchase only fits your budget when it's split into four, it doesn't fit your budget yet.
Below is how buy now, pay later (BNPL) works, what the federal data says about late payments, a worked example of how holiday plans stack up, and a six-step plan for using it safely, or skipping it with a cash plan that still gets the gifts under the tree.
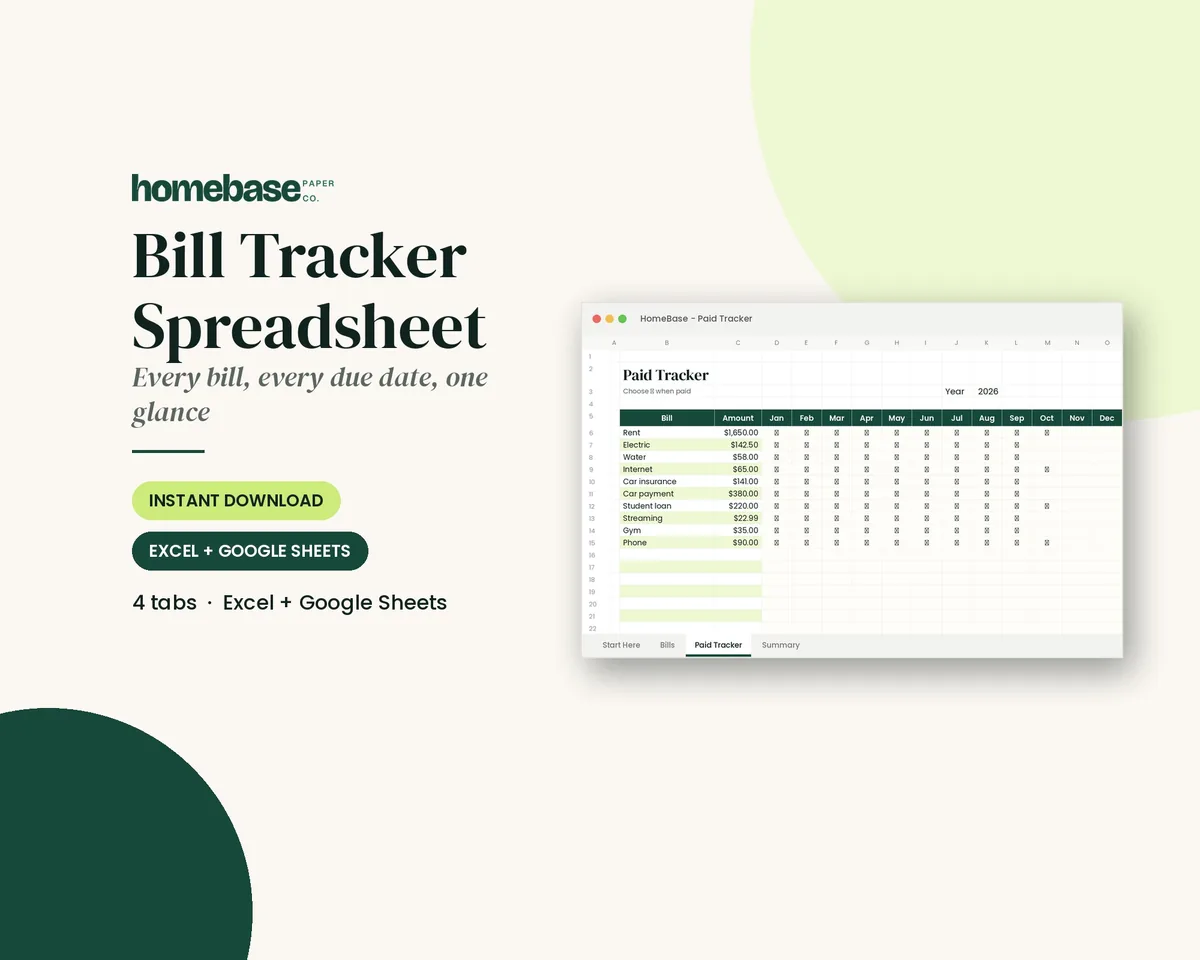
The simplest tool for this is a list of every installment with its due date. Our Bill Tracker Spreadsheet ($4.99, Excel and Google Sheets) turns any bill due within three days red, so a BNPL payment can't sneak up on you. You'll find it with the rest of our budget spreadsheets.
How buy now, pay later works
The Consumer Financial Protection Bureau defines a Buy Now, Pay Later loan as a type of installment loan that lets you buy something now with little or nothing down and pay the rest over four or fewer payments. The most common version splits the price into four interest-free payments made every two weeks. The first one is often due at checkout.
A few details matter more at Christmas than at any other time of year:
- It's still a loan. Even when there's no interest, you've agreed to a payment schedule. Each new purchase is a new loan with its own dates.
- Late fees are common. The CFPB notes that while many BNPL loans don't charge interest, most do charge late fees for missed payments.
- Payments usually come out automatically. You typically connect a debit card, bank account or credit card, and the payments are pulled on schedule, even on Christmas Day.
- Each lender only sees its own loans. Most pay-in-four loans aren't reported to the big credit bureaus, so no one, including the lenders, sees the full stack of plans you've opened. You're the only one who can keep that total.
What the data says about holiday BNPL
Two federal sources give a clear picture of how this goes for real households.
The Federal Reserve's Survey of Household Economics and Decisionmaking, which covers 2025, found that 16 percent of adults used BNPL in the prior 12 months. Among those users:
| What the Federal Reserve found (2025 survey) | Share of BNPL users |
|---|---|
| Paid late at least once in the past year | 26% |
| Were charged extra for paying late | 17% |
| Had a BNPL payment trigger a bank overdraft or NSF fee | 11% |
| Said the main reason was "only way I could afford it" | 29% |
| Said the main reason was "wanted to spread out payments" | 31% |
Late payments were more common among younger users and households earning under $50,000 a year.
The CFPB's own research on BNPL borrowers, released in January 2025, found that about 63 percent of borrowers had more than one BNPL loan open at the same time at some point during the year, and about a third had loans from more than one lender. BNPL borrowers also tended to carry higher balances on credit cards and other unsecured debt.
Put those together and the holiday risk is easy to see. One plan is simple. Three or four plans from different apps, each on its own two-week clock, with autopay pulling from the same checking account, is how a manageable Christmas turns into a January overdraft.
When BNPL for Christmas can make sense (and when to skip it)
Use this table as a quick gut check before you tap the "pay in 4" button.
| It can make sense when... | Skip it when... |
|---|---|
| The gift is already on your list with a set amount | It's an extra you found while browsing |
| The full price fits inside your holiday budget | It only "fits" because it's split into four |
| You know exactly which paychecks cover each payment | You're hoping a bonus or tax refund covers it |
| It's your only open plan, or one of two | You already have two or more plans running |
| The plan charges no interest and you've read the fees | The plan has interest, a long term or unclear fees |
| Your checking account has a cushion for autopay | Your balance often gets close to zero before payday |
If most of your answers land in the right-hand column, a cash plan (more on that below) will cost you less and keep January calmer.
Worked example: how three plans stack into January
Here's a made-up but realistic example. A family sets a $520 gift budget and uses three pay-in-four plans:
- Plan A: $240 of toys on Black Friday, November 27. Four payments of $60.
- Plan B: $160 of clothes on December 5. Four payments of $40.
- Plan C: $120 of gift cards and small gifts on December 12. Four payments of $30.
Each plan takes the first payment at checkout and the rest every two weeks. Here's when the money actually leaves the account:
| Date | Plan A | Plan B | Plan C | Total that day |
|---|---|---|---|---|
| Nov 27 | $60 | $60 | ||
| Dec 5 | $40 | $40 | ||
| Dec 11 | $60 | $60 | ||
| Dec 12 | $30 | $30 | ||
| Dec 19 | $40 | $40 | ||
| Dec 25 | $60 | $60 | ||
| Dec 26 | $30 | $30 | ||
| Jan 2 | $40 | $40 | ||
| Jan 8 | $60 | $60 | ||
| Jan 9 | $30 | $30 | ||
| Jan 16 | $40 | $40 | ||
| Jan 23 | $30 | $30 |
By month, that's $60 in November, $260 in December and $200 in January. Nearly 40 percent of this family's Christmas gets paid for after Christmas, on 11 different dates, from three different apps. A $60 payment comes out on Christmas Day.
Nothing here charged interest. The cost is the risk: one short week in January, one autopay hitting before a paycheck clears, and the late fee or overdraft fee shows up. That's why the plan below starts with writing every date down.
A 6-step plan to use buy now, pay later for Christmas safely
Step 1: Set your holiday budget first
Decide what the whole season can cost before you shop, including gifts, food, travel, cards and decorations. If you don't have a number yet, our holiday budget guide walks through it, and the free Christmas budget calculator suggests a total from your income and bills.
Your BNPL purchases must fit inside that number at their full price. Splitting a payment doesn't make anything cheaper.
Step 2: Cap yourself at one or two plans
Pick a limit before Black Friday and stick to it. One or two plans are easy to track. Past that, the dates start to overlap, as the example above shows. If a third plan is tempting, pay that purchase in full or move it to next year's list.
Step 3: Write down every payment the moment you check out
Don't count on the app's reminders. Before you close the checkout page, record:
| What to record | Example |
|---|---|
| Store and item | Toy store, ride-on car |
| Lender or app | (whichever app you used) |
| Total price | $240 |
| Payment amount | $60 |
| All four due dates | Nov 27, Dec 11, Dec 25, Jan 8 |
| Account it pulls from | Checking ending 1234 |
| Late fee | Check the agreement |
| Return deadline | Check the store's policy |
Put each payment in your bill tracker as its own bill. The Bill Tracker Spreadsheet shows the next due date and days left for every bill and lights up anything due within three days in red. If you'd rather write things down, the Bill Tracker Printable ($3.49) is a paper version. Our guide on how to organize bills shows how to set up the whole system.
Step 4: Set the money aside on purchase day
When you buy, move the remaining three payments into a separate savings bucket or keep them earmarked in checking. That way, the money is spoken for even if December gets expensive. This is the same idea as a sinking fund: save for a known cost before it's due.
Step 5: Track orders and returns
Holiday shopping means packages, and packages sometimes go back. If you return something bought with BNPL, the refund has to work its way through the store and the lender, and scheduled payments may keep coming until it does. Read the lender's return terms before you buy, and keep a list of every online order with its return deadline. The Christmas Budget & Gift Planner ($4.99) includes an Online Order Tracker page plus a budget and gift list for every person, so purchases, returns and spending stay on one page.
Step 6: Close out everything by the end of January
Make your goal "all holiday plans paid off by January 31." Check your tracker on New Year's Day, and if anything's still open, pay it off early if you can. If January gets tight, use our plan for paying off holiday debt to list every balance and pick an order.
If you've already used BNPL this season
You don't need to panic, just get organized today:
- Open each app and list every active plan. Include store purchases you might have forgotten, such as a phone accessory or a pair of boots.
- Add up what's still owed and when. Total it by month, like the example table above.
- Compare it with your next paychecks. If December's payments plus your regular bills are more than what's coming in, you've found the gap early, which is the best time to find it.
- Close the gap. Return unopened items that aren't needed, trim the rest of your gift list, or pay a plan in full while you still have the cash.
- Pause new plans. No new BNPL purchases until the current ones are done.
If you have several balances on credit cards and BNPL apps, the Debt Payoff Planner ($6.99) lets you list up to 10 debts, pick snowball or avalanche, and see your debt-free month.
Better ways to pay for Christmas
BNPL tries to solve a timing problem: the gifts are needed in December, but the money comes in over several paychecks. You can solve that problem without a loan.
Split the cost across your remaining paychecks yourself
Count your paychecks between now and Christmas. Divide your gift budget by that number, and buy in that order: must-haves first, nice-to-haves last. It's the same "spread it out" idea as pay-in-four, with no late fees and no autopay surprises. Our guide on when to start Christmas shopping shows how to map purchases to paydays.
Try layaway for the bigger gifts
Classic layaway holds an item until you have paid in full, so you do not take the gift home on credit. Compare the current store programs and fees in our Christmas layaway guide before you choose a pay-over-time plan.
Use a cash or envelope system for gifts
Pull out the gift budget in cash, or set up separate "envelopes" in a budgeting app or spreadsheet. When the envelope's empty, shopping's done. Our cash envelope system guide explains the setup. Choosing an app? See our pick for the best budget app.
Start next year's Christmas fund in January
Most people turn to BNPL in December because nothing was saved for it. If you put a little aside each month starting in January, next Christmas is paid for before it begins. The Sinking Funds Tracker ($4.99) calculates how much to set aside each month to reach each goal by its date. Our guide to saving money for Christmas has a full plan.
Give less, but give on purpose
As the oldest of three, I learned early that keeping everyone's plans straight matters more than any single gift. A smaller list you can pay for in full usually feels better in January than a bigger one you're still paying off. If you want to suggest a gift draw or a lower limit to your family, our guide on how to tell family no gifts has kind ways to bring it up.
Your next step
Before you shop on Black Friday, write your holiday budget and set your BNPL limit. Then put every installment you open on your bill calendar the minute you check out.
If you want it done for you, the Bill Tracker Spreadsheet ($4.99) handles due dates and red alerts, and the Christmas Budget & Gift Planner ($4.99) keeps your gift budget and online orders in one place. Both are in our budget spreadsheets and holiday shop. For a free start, the Holiday Budget Starter Kit is 3 US Letter pages: a one-page holiday budget, a gift list with per-person limits and a 6-week countdown, emailed to you after you join the list.
This guide is general education, not financial advice. Read each lender's agreement for its own fees and terms.
The Holiday Collection
Give every person a limit and watch what's left
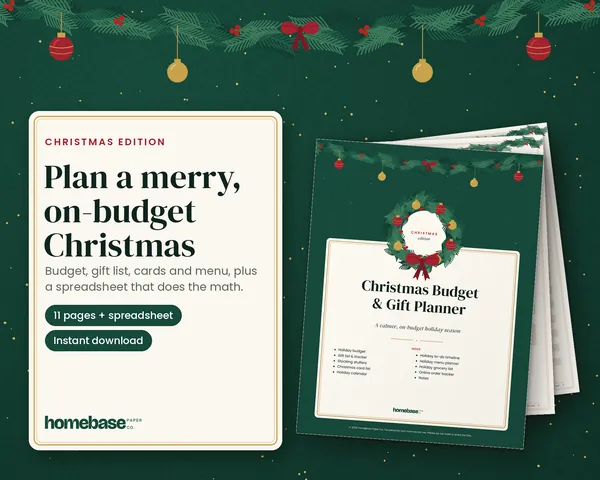
The Christmas Budget & Gift Planner adds up every list for you: a budget for each person, a log of each purchase and the amount left to spend, plus printable gift, card, menu and to-do pages.
- Spreadsheet for Excel and Google Sheets
- 11 printable pages, US Letter + A4
- Instant download, 14-day fix-or-refund promise
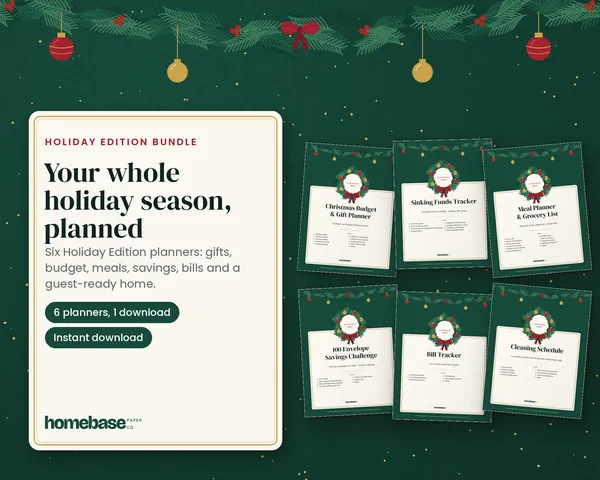
Planning the whole season? See the holiday sets from $7, with early prices through Cyber Monday
Make it easier
Tools for this

Spreadsheets
Bill Tracker Spreadsheet
Bills due in 3 days or less light up red, so nothing slips through.
Printables
Christmas Budget & Gift Planner
Set a budget for every person, log each purchase, and watch what's left - plus printable gift, card, menu and to-do pages.

Spreadsheets
Sinking Funds Tracker
It does the math: how much to set aside each month to hit every goal on time.
Frequently asked questions
Is it a good idea to use buy now, pay later for Christmas? It can be, for one or two planned gifts that already fit your holiday budget. Buy now, pay later spreads a purchase into four payments, usually every two weeks, often with no interest. It turns risky when several plans stack up, because the payments land in late December and January next to your regular bills. A simple test: if the gift only fits your budget when it's split into four, skip the plan and pay in full later or choose a smaller gift.
How do I keep track of buy now, pay later payments? The Bill Tracker Spreadsheet ($4.99) keeps every BNPL installment on one list and turns anything due within three days red. Enter each payment as its own bill with its due date, amount and the account it pulls from, the moment you check out. Don't rely only on app reminders, because each app only knows about its own loans. One list that holds every plan from every app is the only place you'll see your real total.
How many buy now, pay later plans is too many at Christmas? More than two open plans at once is where most holiday budgets start to strain. Each plan runs on its own two-week clock, so three plans can mean a payment almost every week from late November through January. The CFPB found that about 63 percent of BNPL borrowers had more than one loan open at the same time. Set your limit before Black Friday and pay anything beyond it in full.
Does buy now, pay later charge interest? Many pay-in-four plans charge no interest, but most charge late fees if you miss a payment. That's according to the Consumer Financial Protection Bureau. Some longer BNPL loans do charge interest, so read the loan terms before you accept. Even a no-interest plan can cost you if an automatic payment overdraws your checking account and your bank adds its own fee.
What happens if I miss a buy now, pay later payment? You'll usually owe a late fee, and your bank may charge an overdraft fee if autopay pulls money you don't have. In the Federal Reserve's 2025 survey, 26 percent of BNPL users paid late at least once, and 11 percent had a BNPL payment trigger an overdraft or non-sufficient funds fee. If you know a payment will be short, contact the lender before the due date to ask about your options.
Does buy now, pay later affect your credit score? Buy now, pay later can affect your credit score, depending on the lender and the loan. The CFPB says most BNPL loans don't require a hard credit inquiry, and many pay-in-four lenders haven't reported payment history to the credit bureaus, but some longer installment loans do. Read each lender's terms to see what it reports, and treat every plan as a real debt either way.
How do returns work with buy now, pay later? You return the item to the store, and the refund then has to pass through the store and the BNPL lender before your plan is adjusted. Scheduled payments may keep coming until the refund posts, so read the lender's return terms before you buy. The Christmas Budget & Gift Planner ($4.99) includes an Online Order Tracker page, so every holiday order and its return deadline stay in one place.
Is buy now, pay later better than a credit card for Christmas gifts? A no-interest pay-in-four plan paid on time costs less than a credit card balance you carry with interest. But a credit card you pay in full each month also costs nothing, and it keeps all your holiday spending on one statement instead of spread across several apps. The cheapest option of all is paying from money you've already set aside, which is why a Christmas fund started in January beats both.
How can I pay for Christmas without buy now, pay later? Split your gift budget across the paychecks you have left before Christmas and buy in order, must-haves first. That gives you the same spread-out timing as pay-in-four without loans, autopay or late fees. A cash or envelope system for gifts works the same way: when the envelope's empty, shopping's done.
How do I save for next Christmas so I don't need BNPL? The Sinking Funds Tracker ($4.99) calculates how much to set aside each month so next Christmas is paid for by December. Start in January with your total holiday budget, divide it by the months you have, and move that amount to savings each payday. Even a small monthly amount means less to cover in November and December.
What should I do if I already have too many BNPL plans? Stop opening new plans and list every active one today, with what's still owed and when. Total the payments by month and compare them with your upcoming paychecks. Return unopened gifts you don't need, trim the rest of your list, and pay off a plan early if you have the cash. If balances spill into the new year, the Debt Payoff Planner ($6.99) lets you list up to 10 debts and see your debt-free month.
Should I use buy now, pay later on Black Friday? Only for items that were already on your list at a price you planned to pay. Black Friday deals make it easy to add extras, and splitting the price makes each extra feel small. Write your list and your BNPL limit before the sales start, and check whether a deal is real before you buy.
Can buy now, pay later payments come out on Christmas Day? Yes, buy now, pay later payments can come out on Christmas Day. BNPL payments usually come out automatically every two weeks, so one can land on Christmas Day, New Year's Day or a weekend. That's why it helps to write all four due dates down at checkout and keep the money for them set aside. The Bill Tracker Spreadsheet ($4.99) shows days left until each due date so holiday payments don't surprise you.
Is there a free way to plan my holiday budget first? The free Holiday Budget Starter Kit is a good place to start. It's 3 US Letter pages: a one-page holiday budget, a gift list with per-person limits and a 6-week countdown, emailed to you after you join the HomeBase list. Set your total there first, then decide whether any purchase belongs on a payment plan at all.
More from HomeBase
You may also like

Printables
Budget Planner Printable
Twelve undated pages you can print every month: budget, bills, spending, savings and debt.

Spreadsheets
Paycheck Budget Spreadsheet
Enter your bills once. The sheet tells you which paycheck pays each one, all year.

Spreadsheets
Zero-Based Budget Spreadsheet
The 'Left to budget' counter turns green when every dollar has a job.
 Save 57%
Bundles
Ultimate Budget Bundle
All 6 spreadsheets + both printable planners - for less than half the price of buying them separately.
 Club
Monthly club
Money Club
Anyone who wants a clear plan for the month's bills, holiday spending and savings.
Free printable
Never miss a payment: get the free bill calendar
A printable monthly bill calendar with room for due dates, amounts and paydays, so every payment has a plan before the month starts. You'll also get our weekly HomeBase email with simple budgeting and bill-paying tips.

Sources
- Buy Now, Pay Later loan consumerfinance.gov
- Survey of Household Economics and Decisionmaking federalreserve.gov
- Research on BNPL borrowers consumerfinance.gov